
CEDI GAINS AS GOLDBOD INJECTS US$282 MILLION INTO COMMERCIAL BANKS
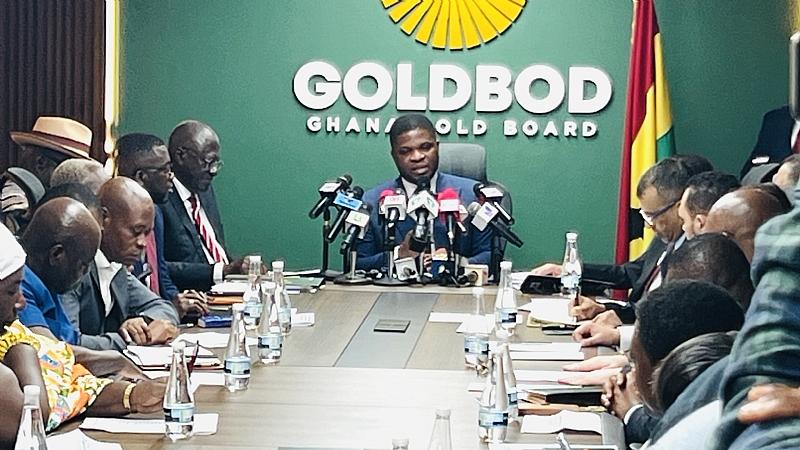
The Ghana Gold Board has sold US$282 million to commercial banks through its GoFX platform, including US$197 million on October 13 and US$85 million on October 15. The additional dollar supply has improved foreign exchange liquidity and helped the cedi stabilize at about GH¢11.68 per dollar on the interbank market. GoldBod says the transactions are spot FX sales backed by foreign exchange earned from gold exports and monitored by the Bank of Ghana.
The Ghana cedi has strengthened against the U.S. dollar after the Ghana Gold Board injected US$282 million into commercial banks over two trading days this week, improving foreign exchange liquidity and easing some of the pressure that had built up from import demand and other dollar obligations.
GoldBod confirmed on Friday, October 16, that it sold US$197 million to commercial banks on Tuesday, October 13, followed by another US$85 million on Thursday, October 15, bringing the total amount supplied during the week to US$282 million. The transactions were conducted through the Board’s GoFX platform under its new structured spot foreign exchange sales framework.
The additional dollar supply has helped improve availability within the banking system at a time when businesses have been demanding more foreign currency to finance imports, settle international payments and meet other commercial obligations ahead of the final months of the year. The cedi, which had faced renewed pressure through much of the third quarter, has responded with modest gains on the interbank market.
GoldBod said the latest sales are part of its statutory responsibility to provide foreign exchange to the domestic market using proceeds generated from Ghana’s gold sector. Under Section 2(b) of the Ghana Gold Board Act, 2025, Act 1140, the Board is empowered to make foreign exchange earned from gold operations available to the country.
According to GoldBod, the transactions are not conventional forex trading. The Board says it earns dollars through its gold operations and then sells those dollars to commercial banks in exchange for Ghana cedis. The cedi proceeds are subsequently used to finance further gold purchases, creating a cycle through which gold exports generate foreign currency that is then fed back into the formal banking system.
The new system is intended to make dollar supply more predictable and transparent. GoldBod ordinarily conducts spot FX sales twice a week, on Tuesdays and Thursdays, with commercial banks submitting requests through the GoFX platform during designated windows. Where requests exceed available supply, allocations are expected to be made proportionately, while transactions are settled on the same day.
The Bank of Ghana monitors the process in real time, according to the Board, while participating banks are required to show that their requests are linked to genuine unmet foreign exchange demand or verified short positions. GoldBod says those safeguards are intended to ensure the dollars are directed toward legitimate market needs rather than speculative accumulation.
The cedi’s response this week has been modest but positive. A live USD/GHS reference checked on October 16 placed the exchange rate at approximately GH¢11.68 to the dollar. That level is broadly consistent with recent interbank quotations and represents an improvement from periods earlier in the month when market pressure had intensified.
The Bank of Ghana’s own published data showed a weighted median rate of GH¢11.6750 on October 14, with a buying rate of GH¢11.6692 and selling rate of GH¢11.6808. The latest market reference remains close to those levels, suggesting that the cedi has stabilized rather than moved through a dramatic appreciation.
Retail rates at forex bureaus remain higher than interbank quotations because bureaux add margins for operating costs, liquidity risk and profit. Recent bureau selling rates have remained around the GH¢12.25 area in some parts of the market, illustrating the persistent gap between the wholesale banking rate and what individual customers may actually pay when purchasing dollars.
That gap is normal within Ghana’s foreign exchange market and should not be confused with the Bank of Ghana’s reference rate. The interbank rate is largely a wholesale benchmark for transactions between financial institutions, while banks and forex bureaux apply additional margins when dealing directly with businesses and individuals.
GoldBod’s latest intervention is particularly important because it comes during a period of elevated demand for foreign exchange. Importers typically increase dollar purchases ahead of the Christmas period as businesses bring in consumer goods, equipment and raw materials. Energy-related payments for crude oil, refined petroleum products and other obligations can also add significant pressure to the market.
GoldBod itself acknowledged those pressures earlier in the week, noting that businesses had been increasing their demand for dollars to finance imports while energy-related payments were also contributing to market tightness. The Board said its US$197 million sale on October 13 helped relieve some of those pressures, with participating banks reportedly receiving the amounts they requested.
The additional US$85 million sold on October 15 extended that support and brought the total for the week to US$282 million. The size of the intervention is significant because improved access to dollars through commercial banks can reduce the incentive for businesses to seek foreign currency through less formal channels, where rates are often higher.
Greater dollar availability can also help narrow the difference between bank and retail market rates if supply remains consistent. When commercial banks are adequately funded with foreign exchange, they are better positioned to meet customer demand without pushing prices sharply higher.
The Board has said its broader objective is to supply up to US$1 billion to commercial banks under revised arrangements linked to foreign exchange generated from the artisanal and small-scale gold sector. That target follows the rollout of the structured GoFX sales framework earlier this month.
The first major sale under the system took place on October 8, when GoldBod sold approximately US$125 million to commercial banks. That transaction was described as the maiden spot FX sale under the new framework and was presented as part of an effort to improve transparency, market confidence and access to foreign currency.
The latest US$282 million therefore represents a substantial acceleration in supply compared with the initial auction. Combined with the US$125 million maiden sale, GoldBod has now provided more than US$400 million to commercial banks within a short period under the new structured arrangement.
GoldBod’s role in the foreign exchange market has grown significantly this year because of Ghana’s strong gold export performance and the government’s decision to centralize parts of the gold purchasing and export system. The institution has exclusive authority over the buying, selling, assaying, valuing and export of gold and other precious minerals under the current legal framework.
The Board says its gold operations generate large volumes of foreign exchange that can be used to strengthen Ghana’s external position while supporting domestic liquidity. In August 2026 alone, GoldBod reported generating US$1.315 billion in foreign exchange, with US$668.21 million sold directly to commercial banks through spot sales and funded forward arrangements.
The government and GoldBod have argued that this structure creates a stronger link between Ghana’s gold resources and the stability of the cedi. Rather than allowing all gold export proceeds to remain outside the domestic financial system, a portion is mobilized and sold through regulated channels to meet legitimate local demand.
The potential benefit is straightforward. When dollar supply increases in a market where demand is high, pressure on the exchange rate can ease. Businesses that previously struggled to obtain foreign currency from banks may find it easier to meet international obligations, reducing competition for scarce dollars and helping stabilize the cedi.
Exchange rate stability has wider implications for inflation and the cost of living. Ghana imports significant quantities of food, fuel, machinery, medicines, vehicles and industrial inputs. When the cedi weakens sharply, importers must spend more local currency to buy the same amount of foreign goods, and those additional costs are often passed on to consumers.
A more stable or stronger cedi can therefore reduce some of the imported cost pressures affecting households and businesses. The effect is not immediate in every sector because companies may have purchased stock at older exchange rates or entered supply contracts in advance, but sustained currency stability can gradually reduce pressure on retail prices.
Fuel is one of the most visible examples. Petroleum products are priced largely in dollars, which means exchange rate movements can directly influence pump prices. A stronger cedi can partially offset increases in international petroleum prices, while depreciation can amplify them.
The same principle applies to pharmaceuticals, electronics, construction materials and manufactured goods. Importers typically build exchange rate risk into their prices, and prolonged currency weakness can raise the cost of everything from medical supplies to food processing equipment.
For commercial banks, the GoldBod intervention provides a direct source of liquidity at a time when customer demand remains high. Banks are often the first point of contact for businesses needing dollars to finance imports or pay suppliers abroad, and shortages can force them to ration supply or quote wider margins.
GoldBod says its digital allocation framework is intended to reduce those uncertainties. Banks submit requests through GoFX, and available dollars are distributed based on demand within a monitored system. The Board argues that this approach is more transparent than irregular or discretionary sales.
The Bank of Ghana’s oversight is also significant because the central bank remains responsible for overall foreign exchange policy and exchange rate stability. GoldBod’s interventions therefore complement rather than replace traditional central bank measures.
The BoG has previously intervened directly in the foreign exchange market through its own auctions, spot sales and liquidity programs. GoldBod now adds another source of supply backed by gold export earnings.
That additional channel could become increasingly important if gold prices remain elevated and export volumes stay strong. GoldBod’s website listed the London Bullion Market Association morning gold price at US$4,181.90 per ounce on October 16, underscoring the high value currently being generated from gold exports.
High gold prices can strengthen Ghana’s foreign exchange position because gold is the country’s largest merchandise export. Greater export earnings increase the pool of dollars available to the economy, although the final effect on the cedi depends on how much of those proceeds actually enter the domestic financial system.
This is where GoldBod’s model becomes central. By buying gold locally, exporting it and directing part of the foreign currency proceeds into commercial banks, the Board is attempting to ensure that export earnings translate more directly into liquidity for the Ghanaian economy.
Critics and analysts will still watch the framework closely because large state-linked foreign exchange operations require transparency, pricing discipline and clear reporting. The rate at which GoldBod sells dollars to banks, how allocations are made and the financial cost of its gold purchasing operations remain important considerations.
GoldBod has responded by emphasizing that the transactions are spot sales rather than speculative currency trading. The Board says it does not buy and sell currencies for profit but converts dollars earned from gold into cedis needed to fund local gold purchases.
That distinction is important because debate has emerged over the Board’s involvement in foreign exchange activity. GoldBod has repeatedly said its authority to supply dollars is explicitly backed by law and is being carried out with Bank of Ghana approval and monitoring.
The latest sales also reinforce the changing structure of Ghana’s currency market. Traditionally, the Bank of Ghana was the dominant public institution providing large volumes of foreign exchange. GoldBod is now emerging as a major additional supplier because of the scale of foreign exchange generated through the gold trade.
That could reduce the burden on central bank reserves if the system functions effectively. Instead of relying entirely on BoG reserves to meet market demand, dollars earned directly from gold exports can be recycled into the banking system.
For Ghana’s external accounts, the approach also supports a broader effort to ensure export earnings are captured through formal channels. Gold smuggling and under-declaration have historically deprived the country of significant foreign exchange, and the government has argued that stronger regulation can increase the amount of export revenue flowing through the official system.
Improved formalization of the gold sector could therefore have both fiscal and currency benefits. More recorded exports can increase foreign exchange inflows, strengthen reserves and provide additional liquidity to banks.
The cedi’s latest gains remain relatively small, however, and should be interpreted cautiously. Foreign exchange markets are influenced by multiple factors, and the US$282 million injection is only one of them.
Government spending, import demand, energy payments, portfolio flows, remittances, export earnings, investor sentiment and central bank policy can all affect the currency. A temporary increase in dollar supply may stabilize the market without necessarily producing a long-term appreciation.
The durability of the current improvement will therefore depend on whether GoldBod can maintain regular supply and whether demand remains manageable. Commercial banks have indicated that sustained liquidity support could help keep the cedi relatively stable, but seasonal demand typically rises toward the end of the year.
December imports are particularly important because retailers and manufacturers often build inventories ahead of the festive season. If that demand exceeds available dollar supply, pressure could return even after the current injection.
Energy sector obligations are another risk. Ghana imports fuel and must also meet foreign currency commitments linked to power generation and petroleum supply. Large dollar payments in those sectors can create sudden spikes in demand.
The authorities will therefore need to balance supply carefully over the coming weeks. Regular injections can help smooth volatility, but excessively large interventions without sufficient underlying foreign exchange earnings could create other financial pressures.
GoldBod’s advantage is that its dollars are generated from gold exports rather than borrowed externally. The Board has repeatedly highlighted this point, arguing that the system provides foreign currency without increasing public debt.
That feature is especially relevant as Ghana continues to manage the aftermath of its debt restructuring and works to strengthen international reserves. Non-debt foreign exchange inflows from exports are generally more sustainable than borrowing for the purpose of defending a currency.
For businesses, the most immediate question is whether bank access improves. A stable published interbank rate has limited value if importers cannot actually obtain dollars at that level. The success of GoldBod’s intervention will therefore depend not only on the cedi’s quoted value but also on whether banks can meet genuine customer demand.
GoldBod says this week’s transactions were specifically designed to address that issue. Its framework requires requests to be linked to real foreign exchange needs, with the goal of ensuring that dollars move from the Board through commercial banks and into productive economic activity.
The latest US$282 million injection is therefore significant not simply because of the headline amount but because of what it represents structurally. Ghana is increasingly using earnings from its gold sector as a direct liquidity tool for the wider economy.
If the system continues to provide predictable dollar supply, it could help reduce volatility in the cedi, improve business planning and lower some of the risk premiums that companies include in their prices.
The benefit would be particularly important for manufacturers and importers that rely on predictable exchange rates when signing supply contracts. Sudden cedi depreciation can make previously profitable transactions unviable, while stability allows businesses to price goods and services with greater confidence.
Consumers could eventually benefit as well if lower exchange rate volatility reduces the frequency of price increases linked to imported goods. The connection is indirect, but currency stability remains one of the most important factors affecting inflation in an import-dependent economy.
The latest intervention comes at a time when the cedi has shown signs of recovering after weeks of gradual depreciation. GoldBod reported earlier this week that the currency had recorded marginal gains for a second consecutive week, with market participants attributing part of that improvement to stronger foreign exchange support.
That trend will now be tested as businesses move deeper into the final quarter. If regular Tuesday and Thursday sales continue at meaningful volumes, the market may have a stronger buffer against seasonal demand.
If the flows slow sharply, pressure could return quickly. The cedi remains sensitive to changes in liquidity, particularly when importers, energy companies and large corporate buyers enter the market at the same time.
For now, GoldBod’s intervention has provided a substantial short-term boost. US$282 million has been added to commercial bank liquidity in just two sessions, while the cedi is holding around GH¢11.68 to the dollar in the interbank market.
The stronger dollar supply does not eliminate the structural pressures facing the currency, but it gives banks more capacity to meet legitimate demand and reduces the immediate scarcity that can drive depreciation.
The next important test will be whether GoldBod maintains its twice-weekly sales and whether those interventions are large enough to match demand without creating distortions.
Market participants will also watch the gap between interbank and forex bureau rates. A sustained improvement in formal dollar availability should, over time, place downward pressure on retail exchange rates if bureaux and banks face less scarcity.
For now, forex bureau customers are still paying more than the interbank benchmark, with selling rates around the GH¢12.25 range in parts of the retail market. That difference remains one of the clearest signs that demand pressure has not disappeared entirely.
The cedi’s latest gains should therefore be viewed as stabilization supported by improved liquidity rather than the beginning of a guaranteed long-term rally.
What has changed is the scale and regularity of GoldBod’s intervention. The Board is now using a structured digital platform to feed substantial amounts of gold-generated foreign exchange directly into commercial banks, adding a new and increasingly influential tool to Ghana’s currency management system.
If those sales remain transparent, predictable and backed by strong gold export receipts, they could help reduce some of the volatility that has repeatedly affected businesses and households.
The immediate picture is encouraging but still conditional. The cedi has gained ground, banks have received a substantial injection of dollars and market liquidity has improved, but year-end import demand and other foreign exchange obligations remain significant.
The real measure of success will therefore come over the next several weeks. If the currency remains stable even as seasonal demand intensifies, GoldBod’s US$282 million intervention will be seen not simply as a temporary injection but as evidence that Ghana’s gold earnings can play a more direct role in supporting the domestic foreign exchange market.